Posted on November 4, 2026
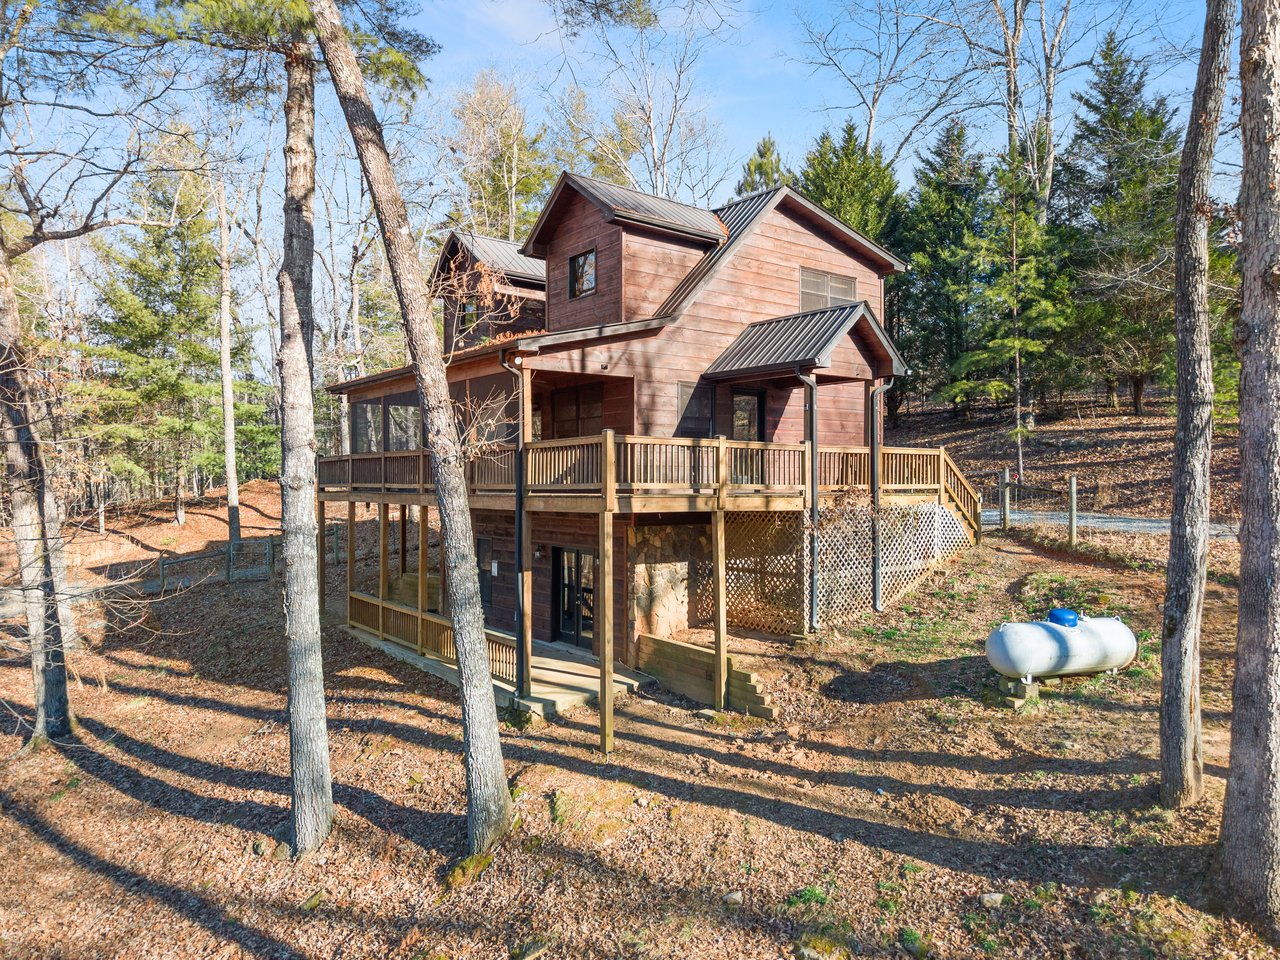
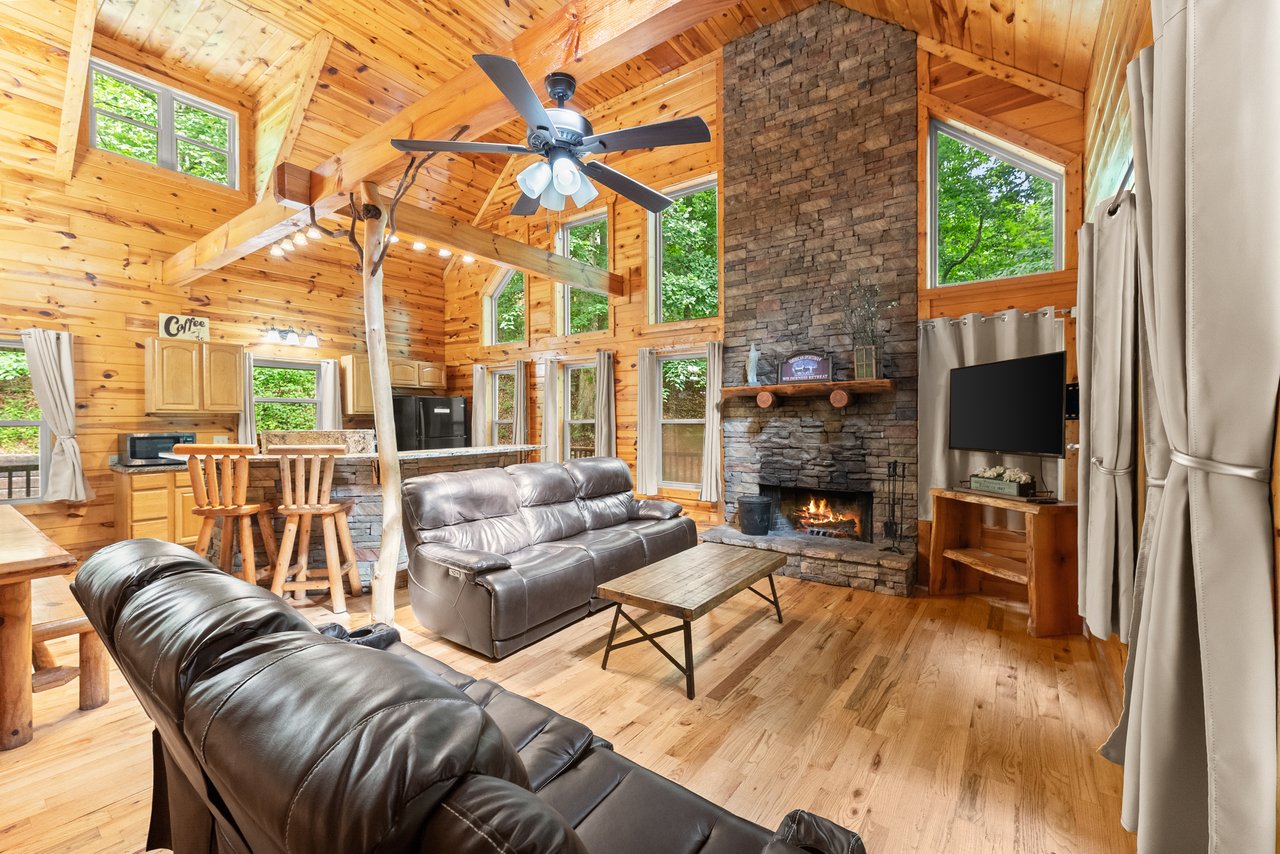
The peak holiday season in the Blue Ridge Mountains is something special. From late October’s peak fall foliage through the Thanksgiving gatherings and cozy Christmas cabin getaways in Ellijay and Helen, our short-term rental market fires on all cylinders. Every year around this time, out-of-market investors and second-home buyers start browsing listings with the same vision: buying a luxury rustic cabin that generates substantial nightly rental revenue while serving as a mountain retreat for their own families.
Then reality hits the underwriting desk.
If you talk to a traditional mortgage broker, they will immediately ask for two years of personal tax returns, W-2s, pay stubs, and a breakdown of your personal debt-to-income (DTI) ratio. If you are a business owner with heavy write-offs, an independent contractor, or someone who already carries a primary mortgage and an auto loan, qualifying for a high-end $600,000 to $900,000 mountain property under conventional Fannie Mae guidelines can feel like trying to haul a boat up Blood Mountain in neutral.
This is where Debt Service Coverage Ratio (DSCR) financing comes into play. More specifically, the ability to qualify for an investment property based solely on projected short-term rental revenue rather than your personal paycheck or past tax returns.
What Makes a DSCR Loan Different for Cabin Investors?
Unlike a conventional agency mortgage that evaluates whether you can afford the home out of your day job, a DSCR loan is a business-purpose, non-QM (non-qualified mortgage) loan that treats the cabin as an independent income-generating asset. Underwriters do not calculate your personal debt-to-income ratio, nor do they scrutinize your personal tax deductions.
Instead, the decision hinges on a single mathematical equation:
DSCR = Gross Monthly Rental Income / Monthly PITIA
(PITIA stands for Principal, Interest, Property Taxes, Hazard/Flood Insurance, and Association or HOA fees.)
Before looking at the ratio thresholds, it helps to understand how lenders evaluate the health of an investment deal:
DSCR of 1.0 (Break-Even): The cabin’s gross rental income matches the monthly debt service dollar for dollar.
DSCR of 1.20 to 1.25 (Preferred Range): The property generates 20% to 25% more revenue than the monthly mortgage obligation, providing a healthy safety net. This tier typically unlocks the most competitive interest rates and loan-to-value (LTV) options.
DSCR Below 1.0 (No-Ratio or Low-Ratio Programs): Select lenders will permit properties where rental income is slightly under the debt service (for instance, an 0.85 DSCR), but they will require higher down payments, larger cash reserves, or stronger personal credit scores to balance out the risk.
The Big Challenge: What If the Cabin Has No Rental History?
Many of the most appealing investment opportunities across Fannin, Gilmer, and Union counties don't come with an established 12-month track record. You might be looking at:
A brand-new custom log cabin built near Aska Adventure Area that has never housed a single guest.
A turnkey vacation home sold by a private family that used it strictly as a personal second home.
An existing cabin that was managed poorly, neglected on Airbnb/Vrbo, and reflects artificially low historical numbers.
If a lender demands a 12-month trailing revenue report (T12) or past Schedule E filings, a deal on an unrented cabin falls through before it starts. Fortunately, a growing segment of non-QM lenders now allows investors to qualify using projected income.
How Lenders Calculate Projected Rental Income on Vacation Cabins
Lenders cannot simply take an investor's word that a four-bedroom cabin with a view of the Cohutta Wilderness will generate $85,000 a year. To establish projected market performance, underwriters rely on specific independent data sources:
AirDNA Rentalizer and Rabbu Market Reports: Forward-thinking DSCR lenders accept specialized third-party short-term rental analytics. These platforms generate projected revenue by analyzing comparable properties within a defined radius, matching bedroom counts, guest capacity, and amenities like hot tubs, outdoor fireplaces, and mountain views. Lenders typically require the report to reflect an average occupancy baseline (usually around 50% to 60%) and compare at least four to five actively operating competitors.
Appraisal With an STR Market Survey (Fannie Mae Form 1007 Custom Addendum): When ordering an appraisal on an investment cabin, the lender instructs the licensed appraiser to complete a rental analysis. While the standard Form 1007 evaluates long-term market rents, an STR-friendly appraiser will prepare an addendum referencing short-term nightly rates (ADR) and seasonal occupancy patterns in the local municipality.
The Long-Term Rent "Fallback" Approach: If a lender is hesitant about pure vacation projections, some will underwrite the loan against what the property would generate as a standard 12-month unfurnished lease using the appraiser’s Form 1007. In high-demand cabin markets, long-term rents are lower than peak holiday short-term earnings, so this method may require putting down 25% or 30% to bring the monthly mortgage low enough to clear a 1.0 ratio.
The Underwriting "Haircut": Managing the Holiday Incline
While a North Georgia cabin can pull in massive daily rates between October foliage tours and New Year's ski and fireside bookings, lenders are well aware that January, February, and early spring can see slower occupancy. To account for seasonality, operating costs, and booking platform fees, underwriters apply conservative safety buffers:
The Projection Discount (Haircut): Most lenders do not credit 100% of an AirDNA projection. Instead, they apply a 15% to 25% discount to the estimated annual gross figure before dividing by 12. If a projection tool forecasts $80,000 annually ($6,666/month), an underwriter applying an 80% haircut will only credit you with $64,000 annually ($5,333/month) for your qualifying income.
Gross Versus Net Accounting: On the positive side, DSCR underwriting uses gross projected revenue. Lenders do not subtract your property management fees, local firewood suppliers, guest supplies, or platform software costs from the top line when computing the qualifying debt service ratio.
Cash Reserve Buffers: Because holiday cabin income arrives in uneven waves, lenders want proof of post-closing liquidity. You should anticipate holding between 3 to 6 months of full PITIA payments in verifiable personal or business bank accounts after your down payment and closing costs are settled.
Practical Qualifications for Buying a North Georgia Cabin With a DSCR Loan
If you want to purchase a cabin in Blue Ridge, Ellijay, Cherry Log, Mineral Bluff, or Morganton using projected cash flow, here is what underwriters expect across standard loan programs:
Credit Score Benchmarks: While some Non-QM products accept credit scores down to 640 or 660, hitting a 700 or 720 FICO score yields dramatically better interest rates and allows you to push leverage up to 80% loan-to-value.
Down Payment Capital: The sweet spot for purchasing a short-term rental property under DSCR terms is 20% to 25% down. If you are using projected income without a past track record, plan for 20% as a baseline and 25% if you want the strongest pricing tiers.
Closing in an LLC: Unlike conventional mortgages where Fannie Mae requires personal-name vesting, DSCR loans allow—and often encourage—closing under an LLC or business entity. This shields your personal assets from guest liability while keeping investment activities cleanly partitioned.
Georgia Closing Mechanics: In Georgia, real estate transactions close through a licensed settlement attorney rather than a title company. You will sign a Security Deed rather than a mortgage. Make sure your funds include Georgia’s intangible recording tax ($1.50 per $500 of the loan amount on long-term notes).
Local Realities: Protecting Your Projected Numbers Before You Put Down Earnest Money
A spreadsheet or projection tool cannot see zoning maps, deed restrictions, or terrain challenges. When evaluating cabins in the North Georgia highlands, ensure your projected figures are rooted in actual local policy:
County Short-Term Rental Ordinances: Fannin County requires vacation rental certificates, local property contact designations, and regular payment of county lodging taxes. Gilmer County similarly regulates STR accommodations, while individual municipalities like the City of Blue Ridge have specific operational guidelines. If a property is located in an unincorporated pocket with grandfathered lodging allowances, confirm that the permit transfers or can be re-issued to a new owner upon closing.
HOA and POA Covenants: Several premier mountain developments—such as Coosawattee River Resort in Ellijay or Walnut Mountain—have distinct rules regarding rental registrations, guest fees, gate access passes, and parking limits. Other subdivisions strictly ban rentals with durations of less than 30 or 90 days. An underwriter won’t catch an HOA restriction until the questionnaire arrives late in escrow, which can endanger your deposit if not vetted during the due diligence period.
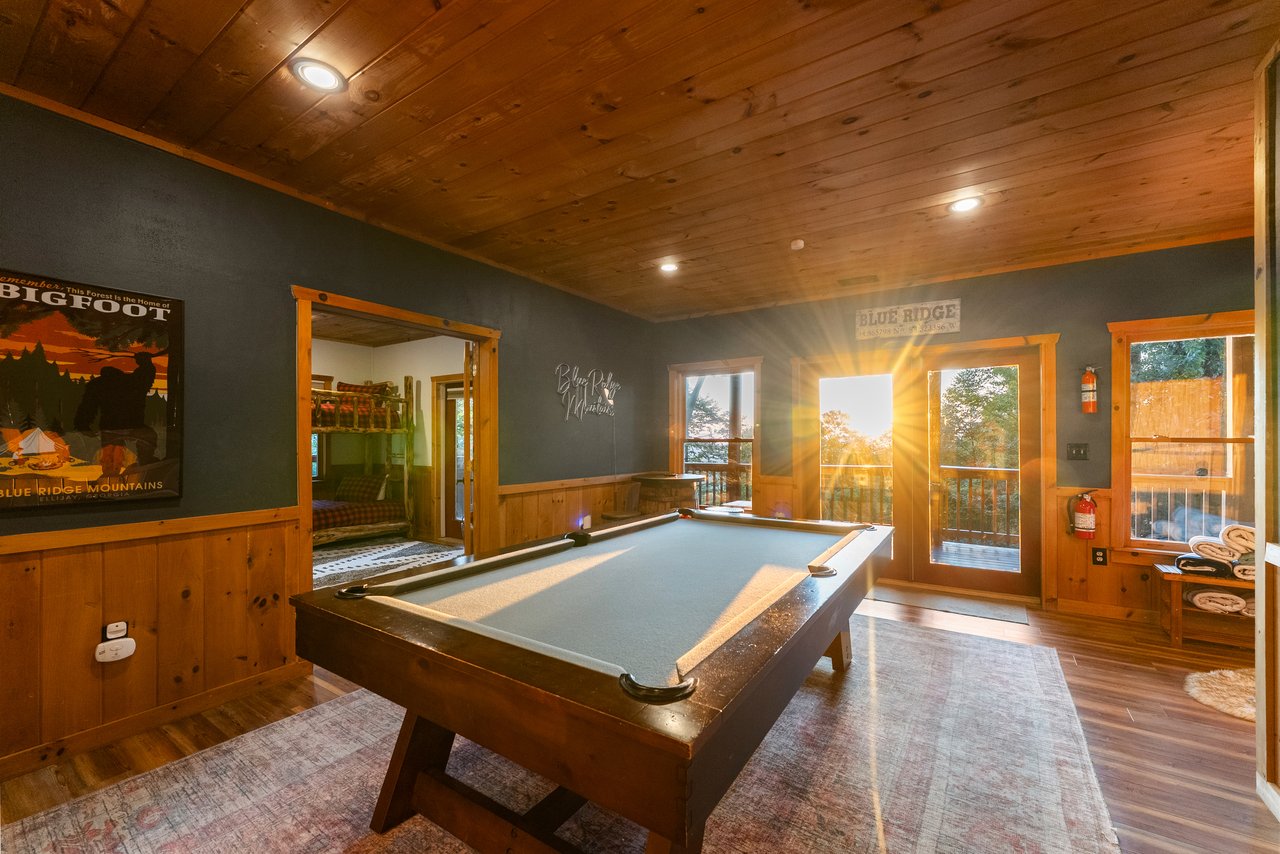
The "Amenity Multiplier" for Winter and Holiday Bookings: In our mountain market, cabins with identical square footage can perform drastically differently based on three amenities: a well-maintained hot tub, an indoor game room or movie den, and a usable outdoor fire feature with mountain sunset views. AirDNA projections will treat two properties of equal size similarly, but prospective guests searching for a holiday getaway will routinely pay $100 to $200 more per night for the cabin that offers private, winter-ready outdoor living spaces.
Financing a vacation cabin doesn’t have to depend on whether your personal tax returns make conventional lenders comfortable. By pairing property-level revenue projections with an asset-based DSCR loan, real estate buyers can evaluate properties based on what matters most: the ability of the cabin to pay for itself while generating long-term equity in our mountain communities.
As our local winter market gears up and travelers book their holiday stays across North Georgia, taking a hard look at the underlying property math, local rental covenants, and debt service coverage options is the most reliable way to turn a mountain retreat from a lifestyle daydream into a dependable commercial asset.